Launch offer — valid today only

📄 Digital book in PDF · read it on your phone or print it

The Federal Return in Drawings, for Tax Preparers: From Intake to E-File in 9 Steps One Tax Topic on Every Page

Filing status, dependents, the W-2 and 1099s, income, adjustments, credits, Form 8867 and e-file. Every topic gets its own page: the drawing first, then what you need to remember. 68 illustrated pages.

START STUDYING THIS WAY

🔒 Secure checkout · PDF by email · 30-day guarantee

Every topic, its own pageEach rule drawn, with the explanation right beside it
68 illustrated pages9 parts, from the preparer's job to the review checklists
Up-to-date sourcesIRS Publications 17, 501 and 596, plus the Form 1040 instructions
PDF by emailFormat

Look Inside the Book

Every page has one big drawing and a box with the tests, steps and lines you need to know:

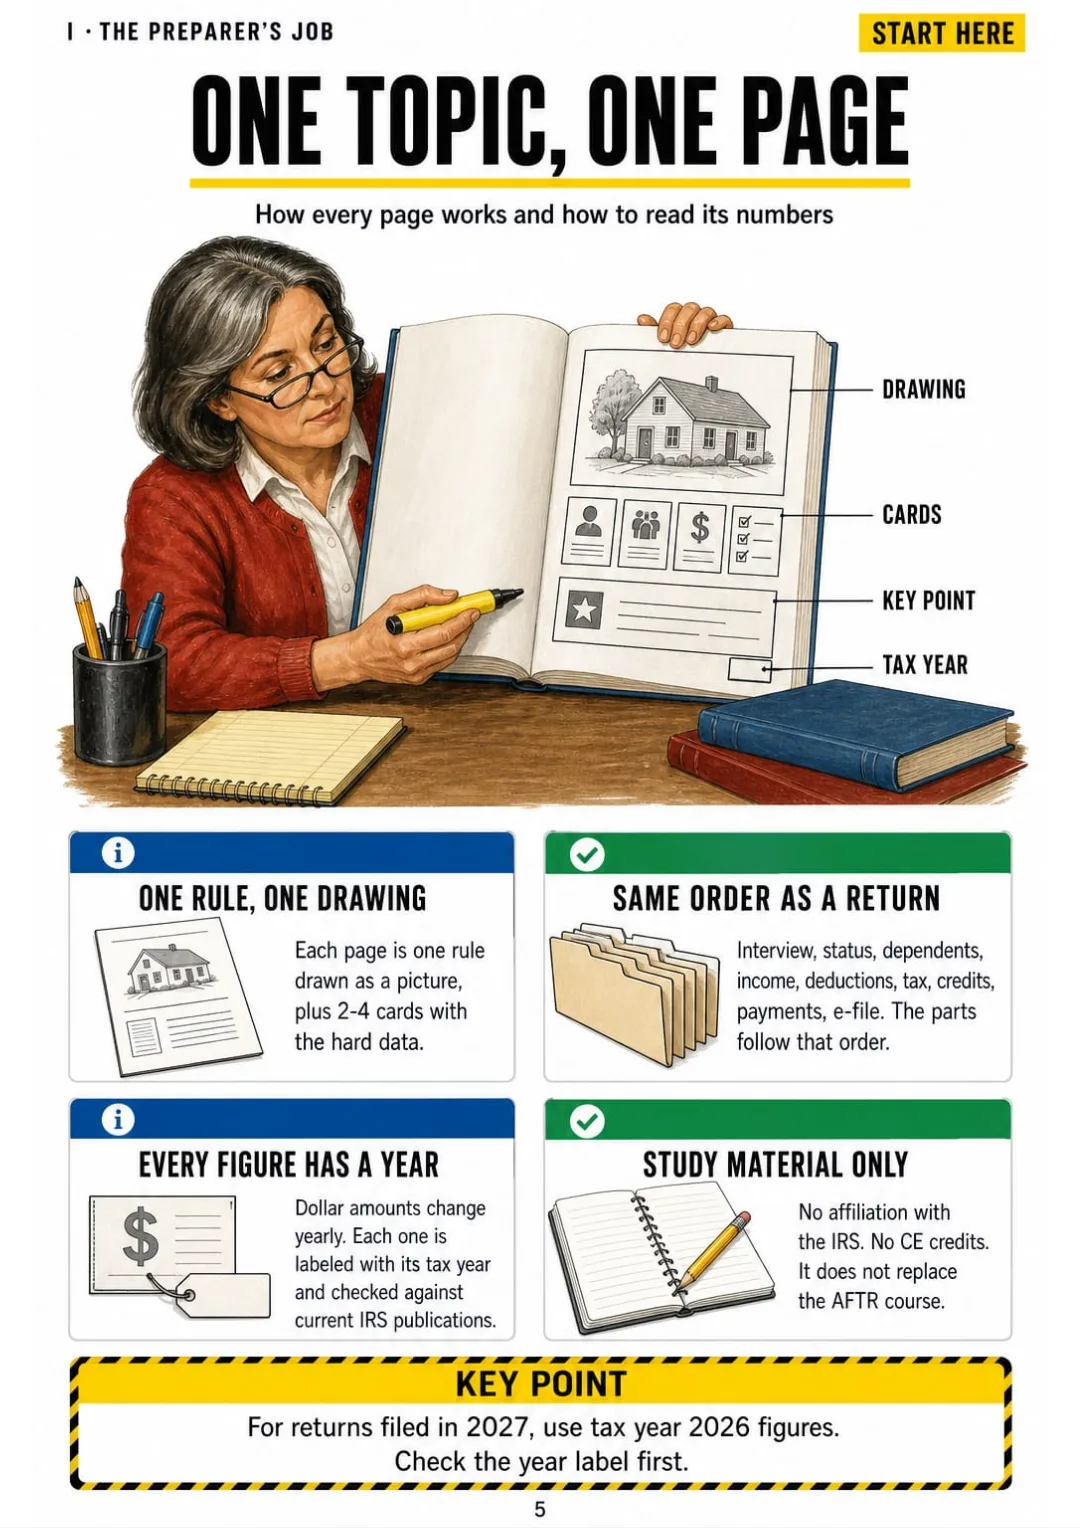
Every page: one drawing, 2-4 cards, and each dollar figure tagged with its tax year
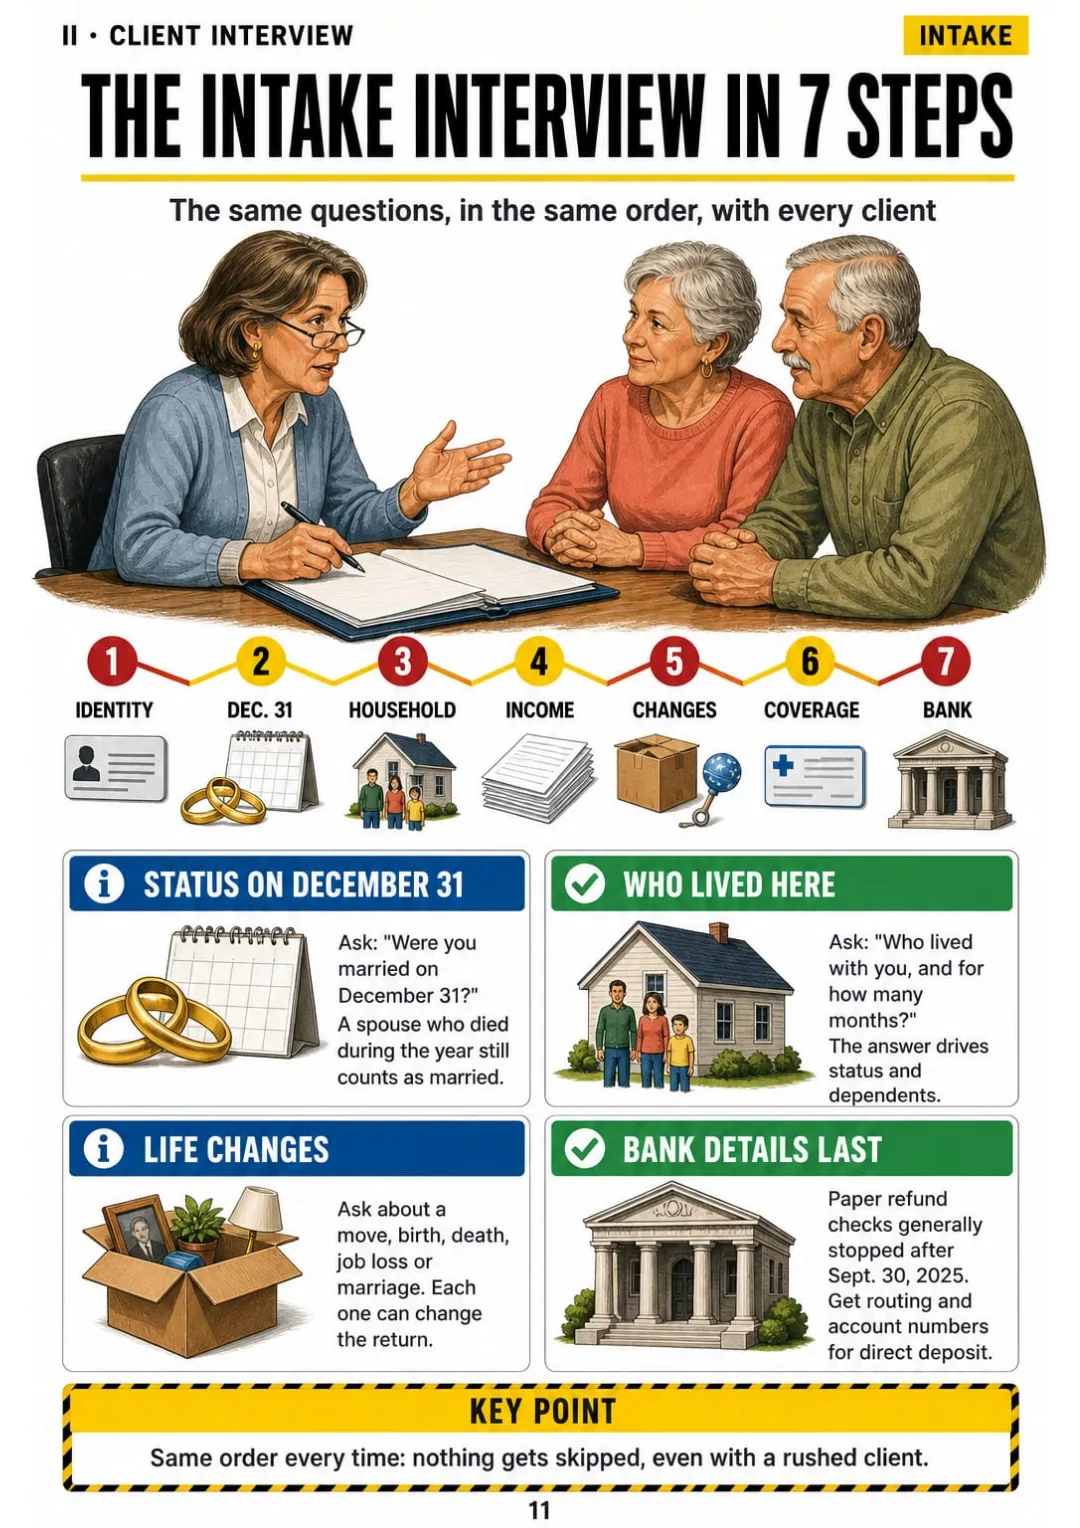
Identity → Dec. 31 status → household → income → changes → coverage → bank
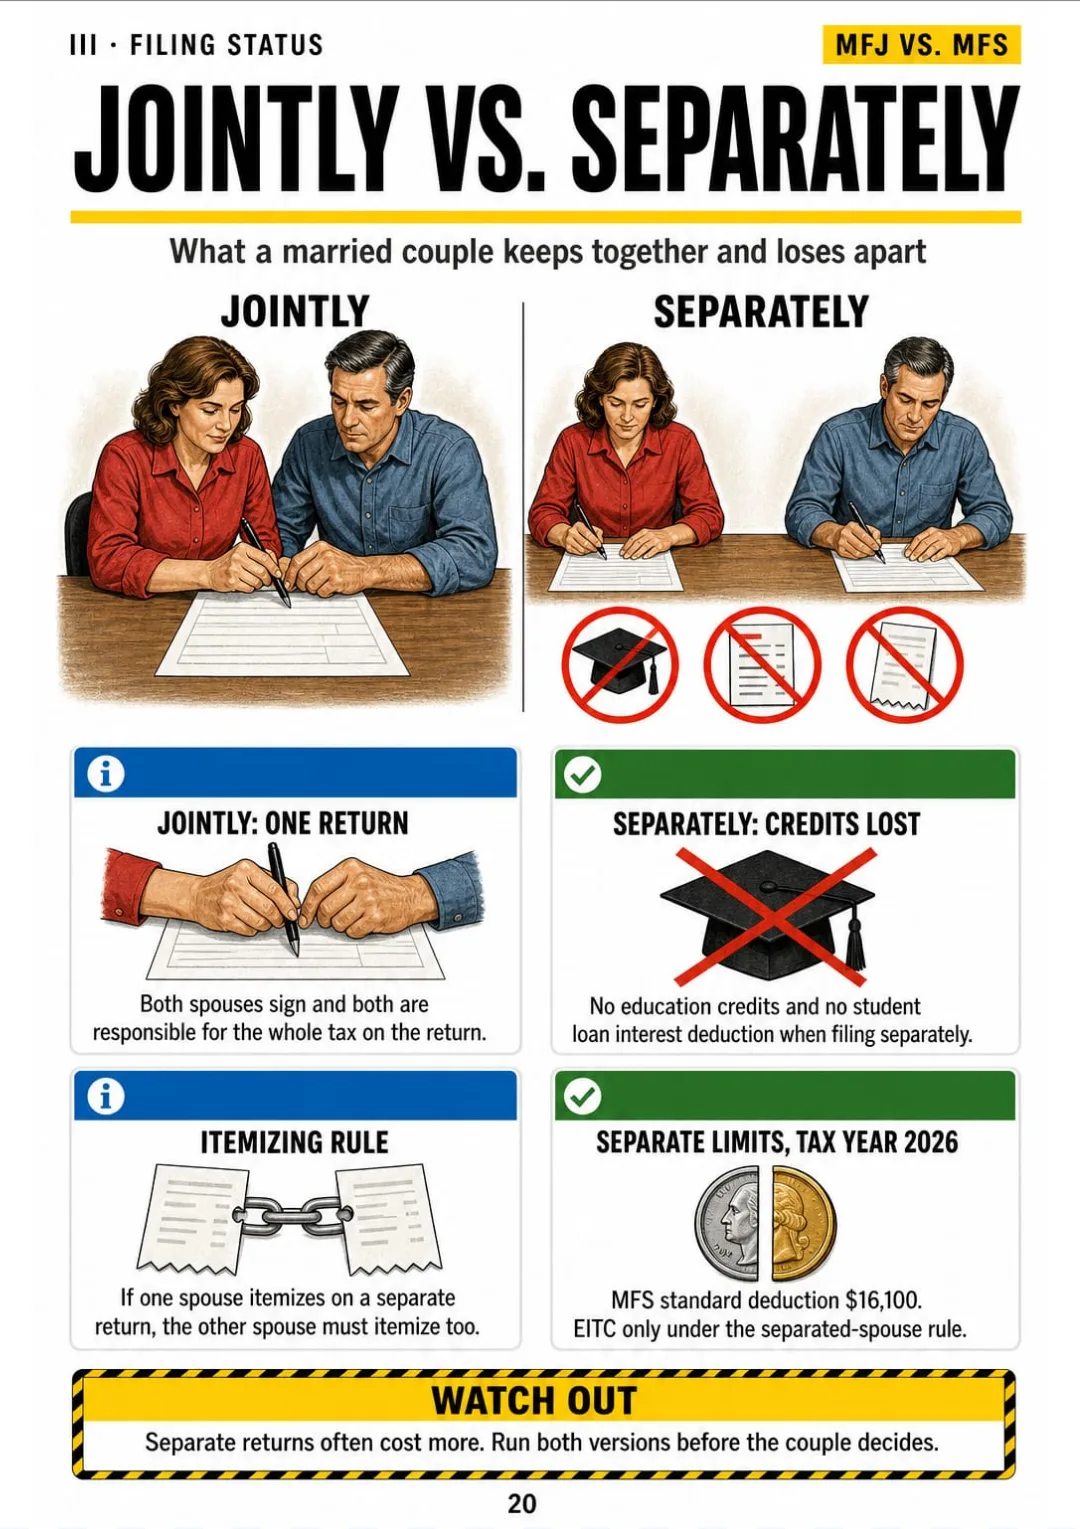
MFS loses education credits and student loan interest; one itemizes, both itemize.
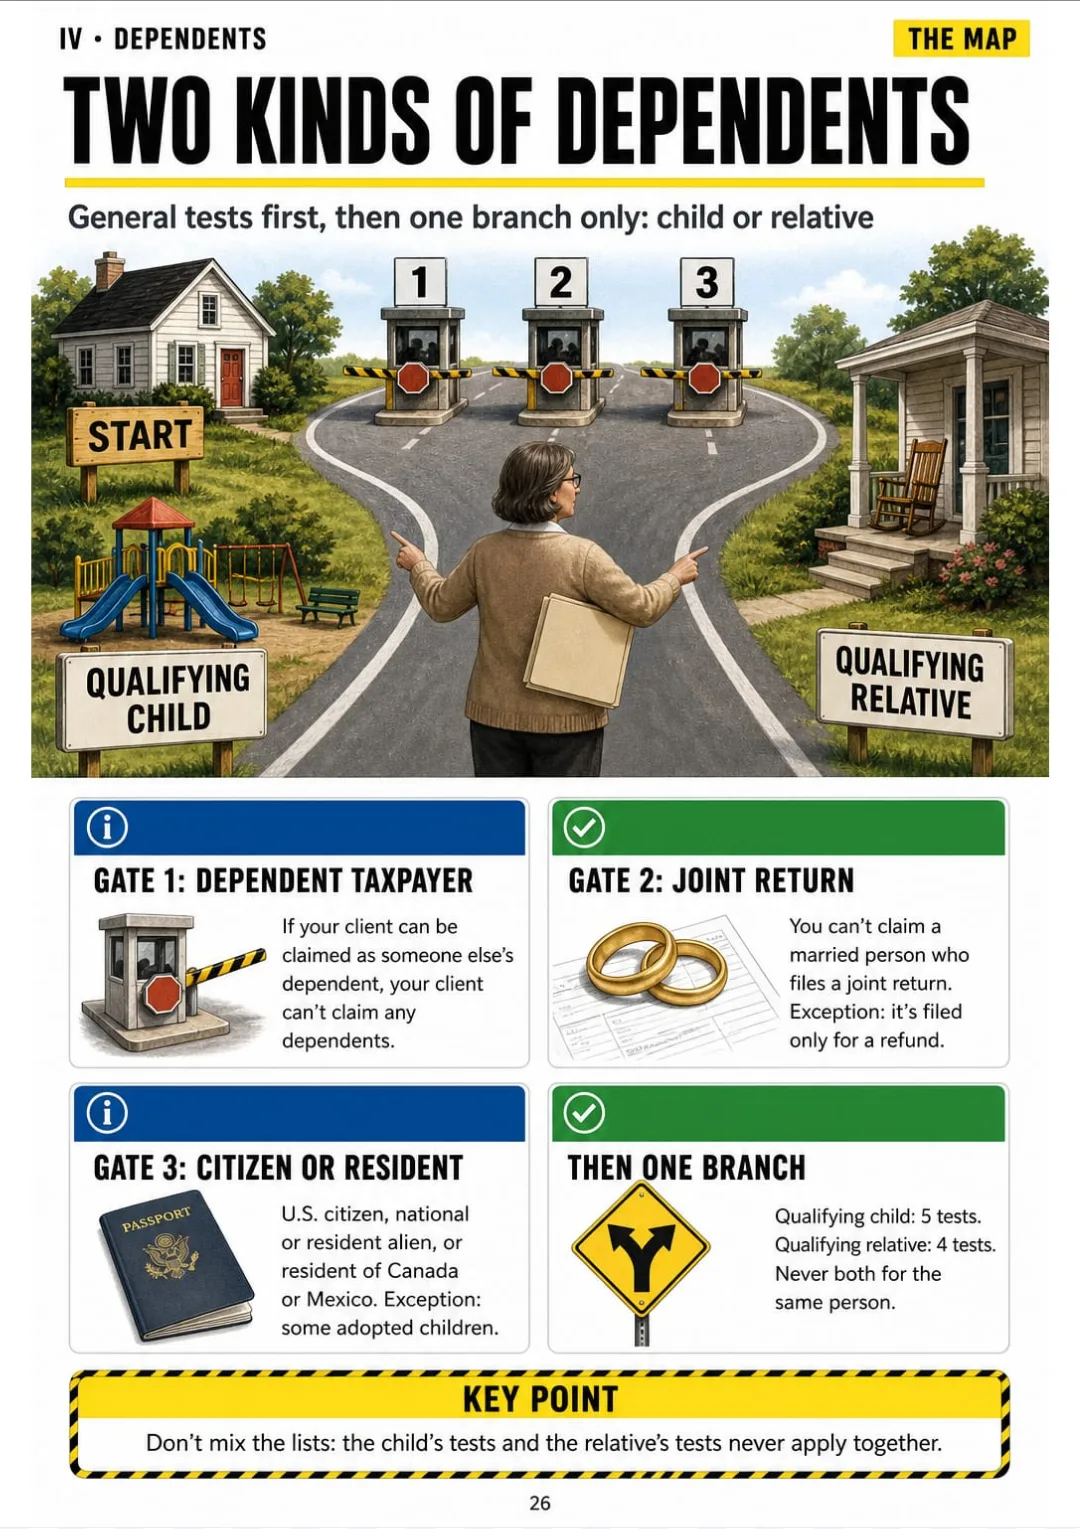
3 general gates, then one fork: qualifying child (5 tests) or qualifying relative (4 tests).
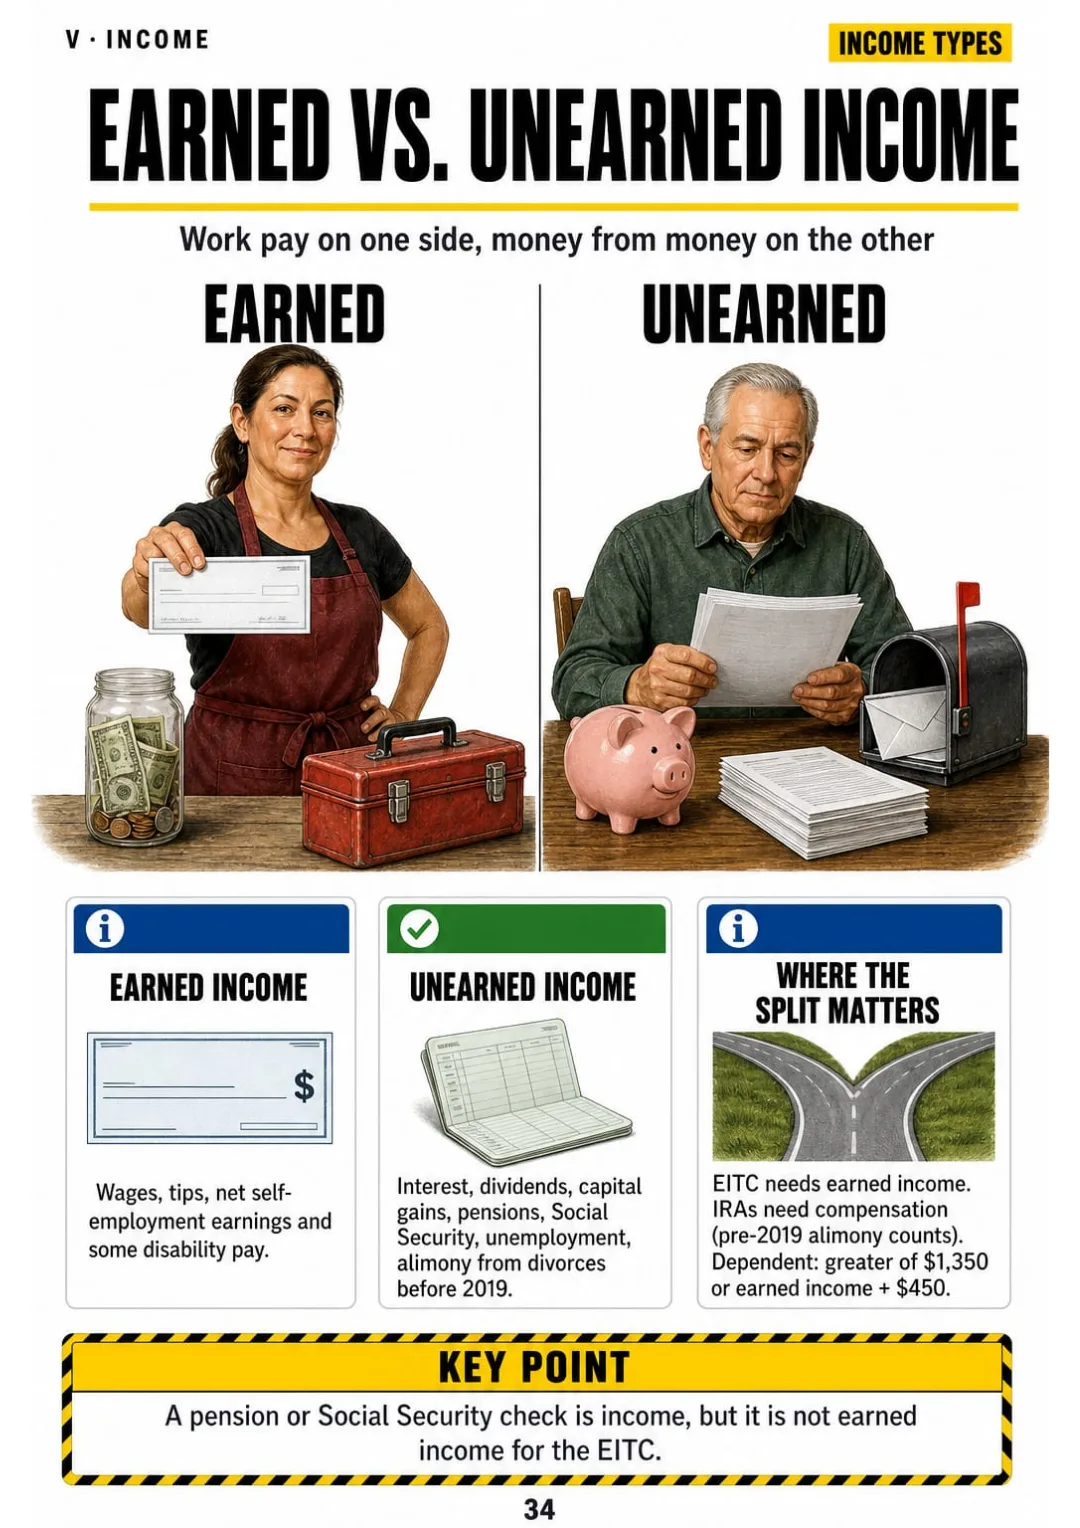
Earned vs. unearned: the split that decides the EITC, the IRA and a dependent's deduction
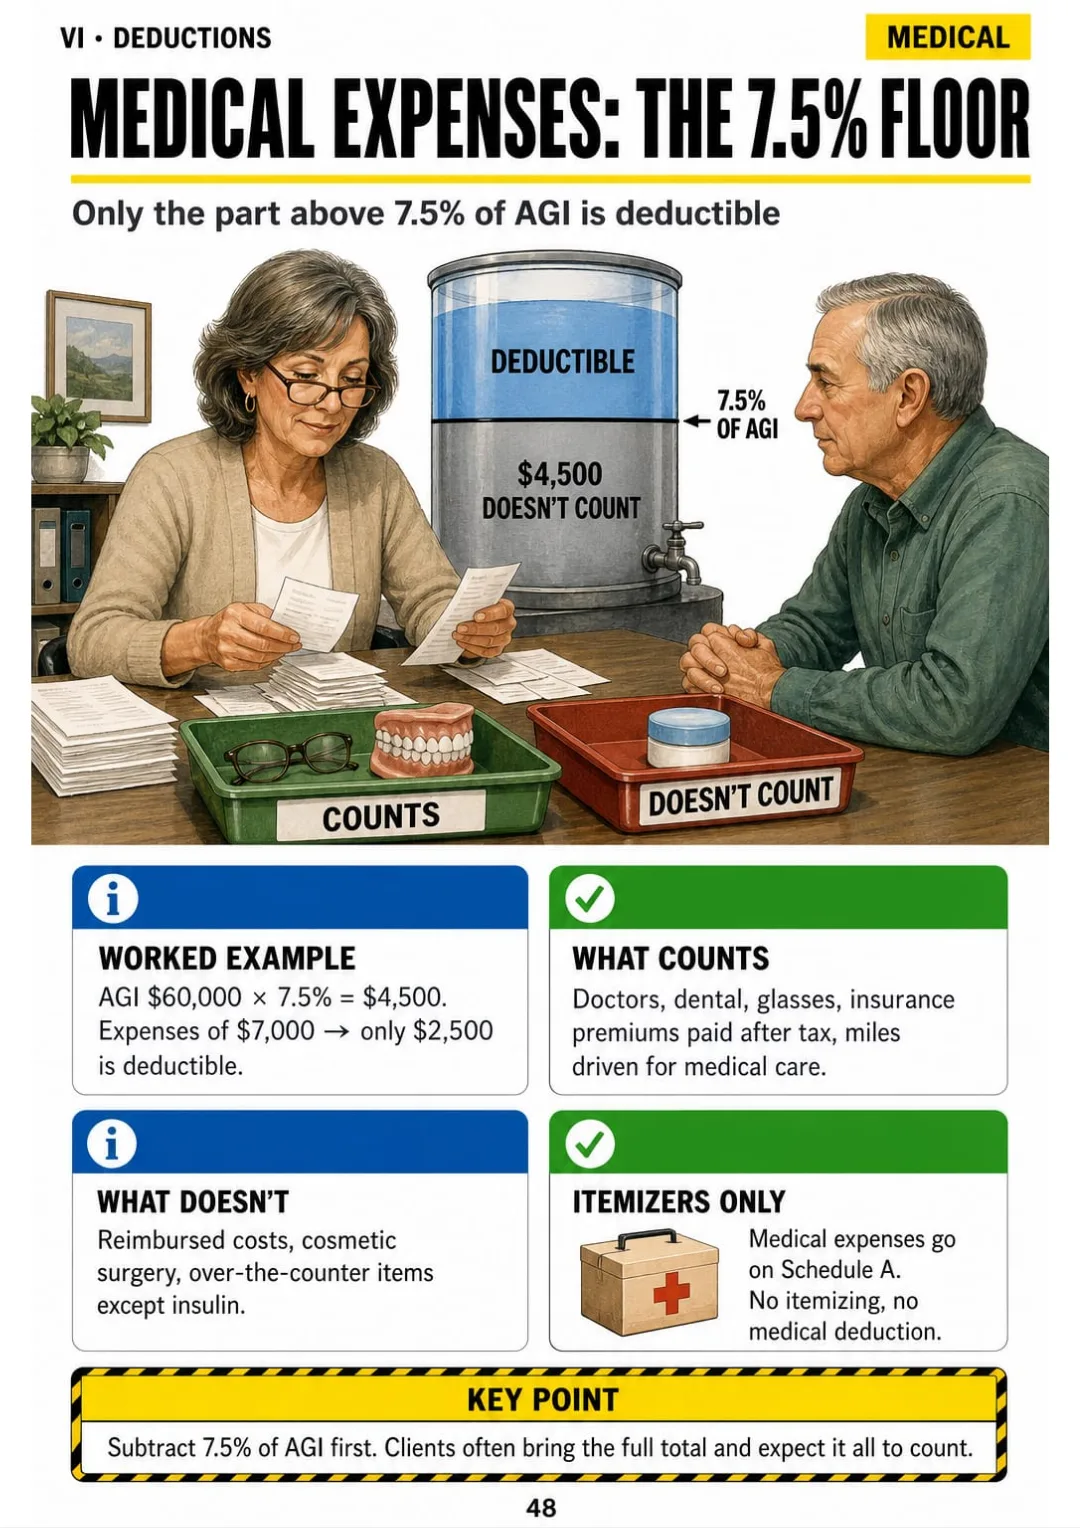
AGI $60,000 → the first $4,500 of medical costs doesn't count.
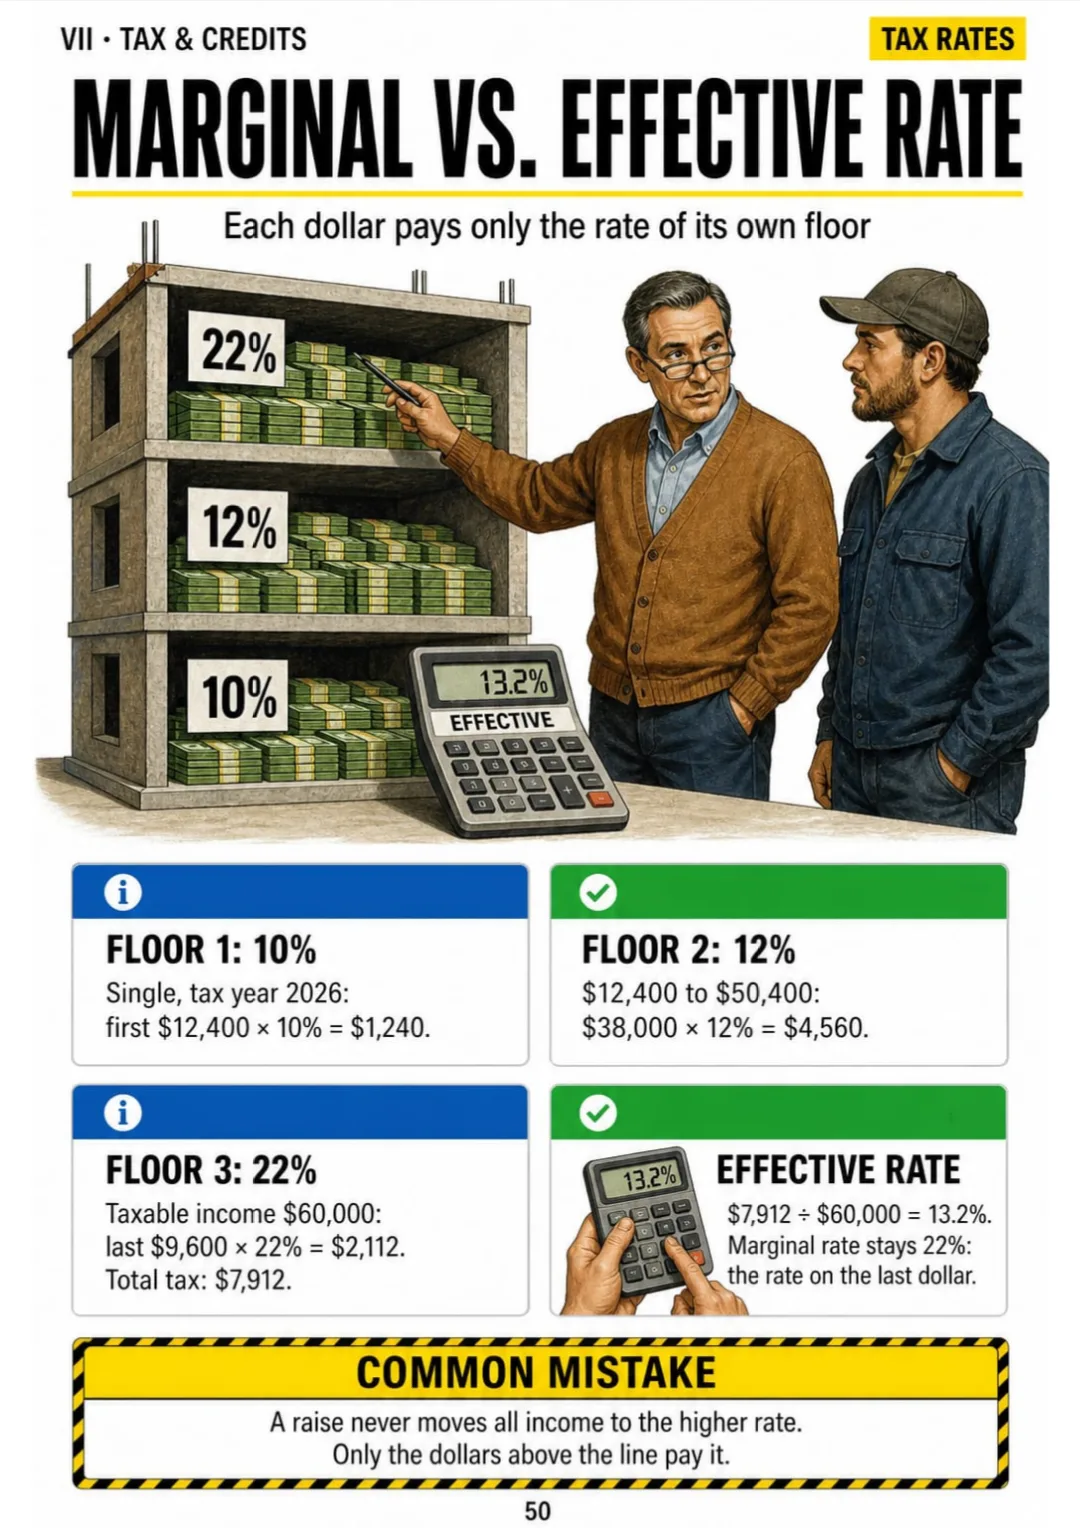
$60,000 taxable income, single 2026: 22% marginal rate, 13.2% effective rate.
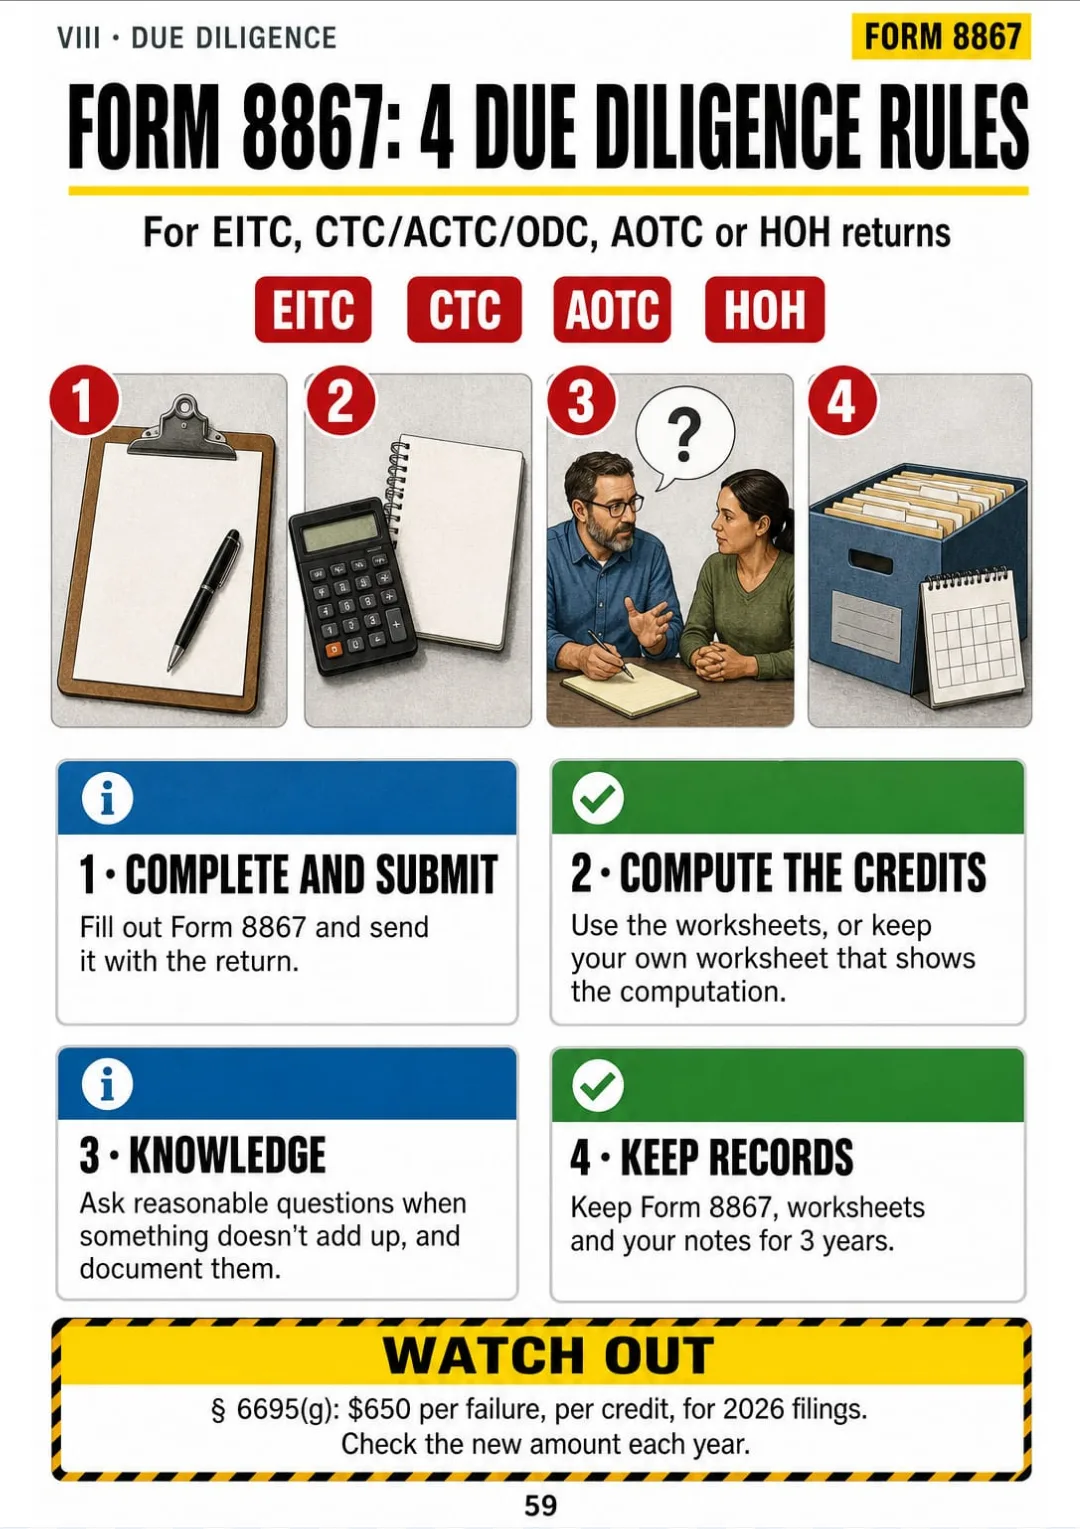
Form 8867: 4 requirements, $665 per failure on returns filed in 2027, up to $2,660 per return.

Swipe to see more →

These are real pages from the book. The table of contents is the full one: 9 parts and 64 topics.

The Problem Isn't You. It's How It Was Explained to You.

You're at your desk with a client across from you. She's married, her husband moved out in the spring, and her son lives with her. Head of household or married filing separately? She's waiting for your answer.

You've read this in Publication 501. But there, it's all paragraphs: tests, exceptions, then exceptions to the exceptions. With a client watching, those paragraphs don't come back to you in order.

MFS loses education credits and student loan interest; one itemizes, both itemize.

In the book, filing status is one decision tree. It starts with a single question, married on December 31?, and every branch ends in one of the 5 filing statuses. You follow the branch that fits your client's facts.

The rest works the same way: qualifying child vs. qualifying relative, the W-2 boxes, adjustments before AGI, the EITC path, Form 8867. Each one has its own page.

You look at the tree, run the client's facts through it and give the answer without reaching for the manual.

COMPARE FOR YOURSELF

The Same Topic, Two Ways to Study It

THIS
  • The manual: line after line after line
  • The intake interview explained only in words
  • You sit down with the client still unsure
Prior to preparing the return, the preparer should conduct a thorough interview with the taxpayer, verifying identity through acceptable documentation and confirming taxpayer identification numbers for all individuals listed. Marital status as of the last day of the tax year must be established, together with the composition of the household and the residency of any persons who may qualify as dependents. All sources of income should be identified, along with any changes in circumstances during the year, health coverage information and bank account details for direct deposit.
FOR THIS
  • The intake interview in one drawing
  • The 7 steps in one box
  • You see it and you get it
Identity → Dec. 31 status → household → income → changes → coverage → bank
CONTENTS

Take a Look at the 9 Parts and 64 Topics

The preparer's job, the client interview, filing status, dependents, income, adjustments and deductions, tax and credits, due diligence and e-file, and the final review: 68 pages, all illustrated

IThe Preparer's Job · pp. 5-10
  1. How to Use This Book: One Topic, One Page
  2. The Tax Staircase: The Whole Return in 9 Steps
  3. PTIN: Who Needs One and When to Renew
  4. The Annual Filing Season Program in One Drawing
  5. Who Can Do What: Credentials and Representation
  6. Circular 230 Duties You Use Every Day
IIThe Client Interview and the Paper Box · pp. 11-18
  1. The Intake Interview, Always in the Same Order
  2. Identity First: IDs, SSNs and the IP PIN
  3. Form W-2: The Boxes That Matter
  4. The 1099 Family at a Glance
  5. Form 1099-R and Its Distribution Codes
  6. SSA-1099 and Social Security Benefits
  7. Forms 1098, 1098-T and 1098-E
  8. Form 1095-A: The Marketplace Form You Can't Skip
IIIFiling Status · pp. 19-25
  1. The Filing Status Decision Tree
  2. Married Filing Jointly vs. Separately
  3. Head of Household: The 3 Tests
  4. Considered Unmarried: The Married Client Who Can Be HOH
  5. Cost of Keeping Up a Home: What Counts
  6. Qualifying Surviving Spouse
  7. When More Than One Status Fits
IVDependents · pp. 26-33
  1. Two Kinds of Dependents: The Map
  2. Qualifying Child: The 5 Tests
  3. Qualifying Relative: The 4 Tests
  4. The Support Test Worksheet
  5. Temporary Absences and Born or Died During the Year
  6. Tie-Breaker Rules: Two People, One Child
  7. Divorced or Separated Parents and Form 8332
  8. SSN, ITIN and the Credits That Depend on Them
VIncome · pp. 34-41
  1. Earned vs. Unearned Income
  2. Interest and Dividends: Schedule B
  3. Capital Gains: Short Term vs. Long Term
  4. Selling the Home: The Exclusion
  5. Retirement Distributions and the 10% Additional Tax
  6. Unemployment, State Refunds and Other 1099-G Income
  7. Self-Employment Income: Schedule C in One Page
  8. Self-Employment Tax: The 92.35% Step
VIAdjustments and Deductions · pp. 42-49
  1. Adjustments: The Step Before AGI
  2. Traditional IRA Deduction and the Workplace Plan
  3. The Standard Deduction and Its Add-Ons
  4. Itemized Deductions: Schedule A in 4 Boxes
  5. The New Deductions on Schedule 1-A
  6. Charitable Gifts: What Records the Client Needs
  7. Medical Expenses: The 7.5% Floor
  8. Education: Tuition Isn't a Deduction Anymore
VIITax, Credits and Payments · pp. 50-58
  1. Marginal vs. Effective Rate
  2. Nonrefundable vs. Refundable Credits
  3. Child Tax Credit and Credit for Other Dependents
  4. Earned Income Tax Credit: The Eligibility Path
  5. The Dependent Care Credit
  6. AOTC vs. Lifetime Learning Credit
  7. Premium Tax Credit: Reconciling Form 8962
  8. Payments: Withholding, Estimates and the Safe Harbor
  9. Refund or Balance Due: The Last Step
VIIIDue Diligence, E-File and Safeguarding Data · pp. 59-64
  1. Form 8867: The 4 Due Diligence Requirements
  2. The Knowledge Requirement in Practice
  3. Form 8879 and the E-File Signature
  4. Rejections: The Codes You Fix Most Often
  5. Protecting Client Data: The WISP
  6. Preparer Penalties and What Triggers Them
IXReview and Checklists · pp. 65-68
  1. The Whole Return on One Page
  2. Desk Checklist Before You Transmit
  3. Frequent Mistakes, Drawn Wrong Next to Right
  4. How to Review for the Annual Refresher Test

One Page, One Topic, All Clear

Think of it this way:

It's January. A client sits down with a W-2, a 1099-R and a 1098-T and asks whether her son in college still counts as her dependent. You need the answer while she's still in the chair.

You open the page on the two kinds of dependents and there it is, drawn: 3 general gates, then one fork. Qualifying child with its 5 tests on one side, qualifying relative with its 4 tests on the other.

Earned vs. unearned: the split that decides the EITC, the IRA and a dependent's deduction

Same with filing status, the W-2 boxes, adjustments before AGI, the EITC path and Form 8867: each one on its own page.

Tax Preparer Basics Illustrated is 9 parts and 64 topics, all drawn, and it ends with the whole return on one page, a desk checklist and the frequent mistakes drawn wrong next to right.

What you see drawn, you don't have to memorize.

What's Inside Tax Preparer Basics Illustrated:

Ipp. 5-10

The Preparer's Job

How the book works, the tax staircase in 9 steps, the PTIN, the Annual Filing Season Program, credentials and representation, and the Circular 230 duties you use every day.

IIpp. 11-18

The Client Interview and the Paper Box

The intake interview in order, identity and the IP PIN, the W-2 boxes that matter, the 1099 family, 1099-R codes, SSA-1099, the 1098 forms and Form 1095-A.

IIIpp. 19-25

Filing Status

You pick the right status with the client watching: the filing status decision tree, joint vs. separate, the 3 head of household tests, considered unmarried, keeping up a home, qualifying surviving spouse and what to do when more than one status fits.

IVpp. 26-33

Dependents

The map of the two kinds of dependents, qualifying child and qualifying relative tests, the support worksheet, temporary absences, tie-breakers, Form 8332 and the SSN or ITIN rules behind the credits.

Vpp. 34-41

Income

Earned vs. unearned income, Schedule B, short- and long-term capital gains, the home sale exclusion, retirement distributions, 1099-G income, Schedule C and self-employment tax.

VIpp. 42-49

Adjustments and Deductions

Adjustments before AGI, the IRA deduction, the standard deduction and its add-ons, Schedule A in 4 boxes, the new Schedule 1-A deductions, charitable records, medical expenses and education.

VIIpp. 50-58

Tax, Credits and Payments

Marginal vs. effective rate, refundable vs. nonrefundable credits, the child and dependent credits, the EITC path, the dependent care credit, AOTC vs. Lifetime Learning, Form 8962, payments and the last step.

VIIIpp. 59-64

Due Diligence, E-File and Safeguarding Data

The 4 due diligence requirements on Form 8867, the knowledge requirement, Form 8879, the rejection codes you fix most often, the WISP and preparer penalties.

IXpp. 65-68

Review and Checklists

The whole return on one page, the desk checklist before you transmit, frequent mistakes drawn wrong next to right, and how to review for the annual refresher test.

At the end of the book: The whole return on one page, a desk checklist before you transmit and the frequent mistakes drawn wrong next to right.
Plus: 2 Free Books

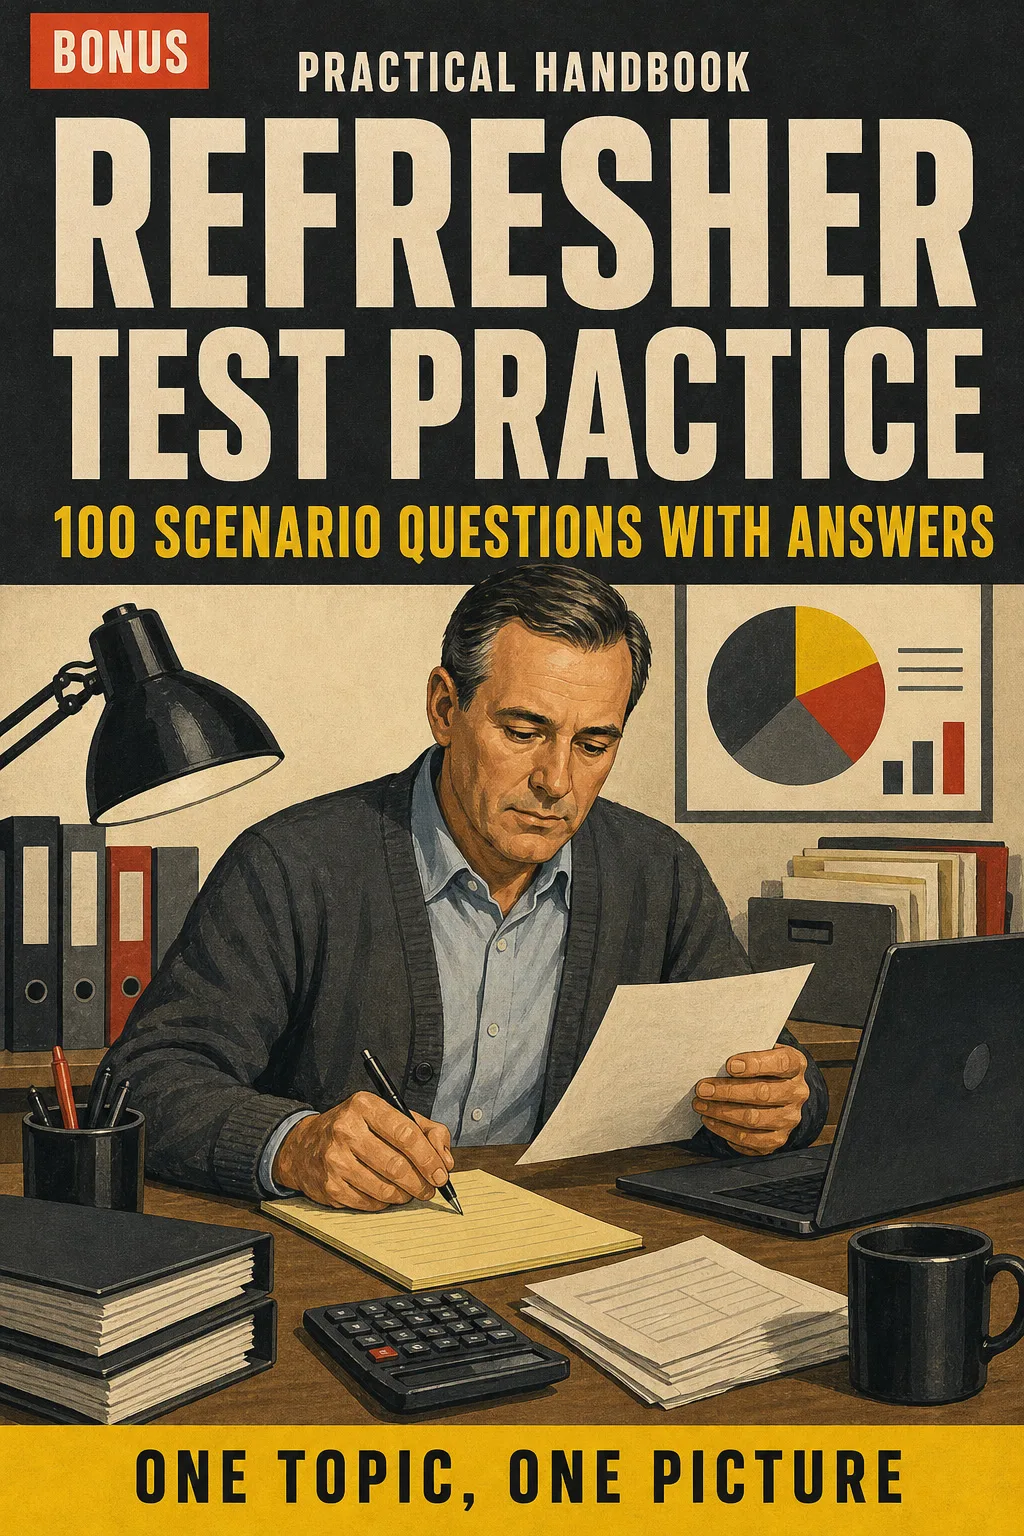
Refresher Test Practice: 100 Scenario Questions with Answers

BONUS 1: «Refresher Test Practice: 100 Scenario Questions with Answers»

Value on its own: US$ 17.90

Practice multiple-choice client scenarios like the annual refresher test, with the reason behind every answer so you know where to look again.

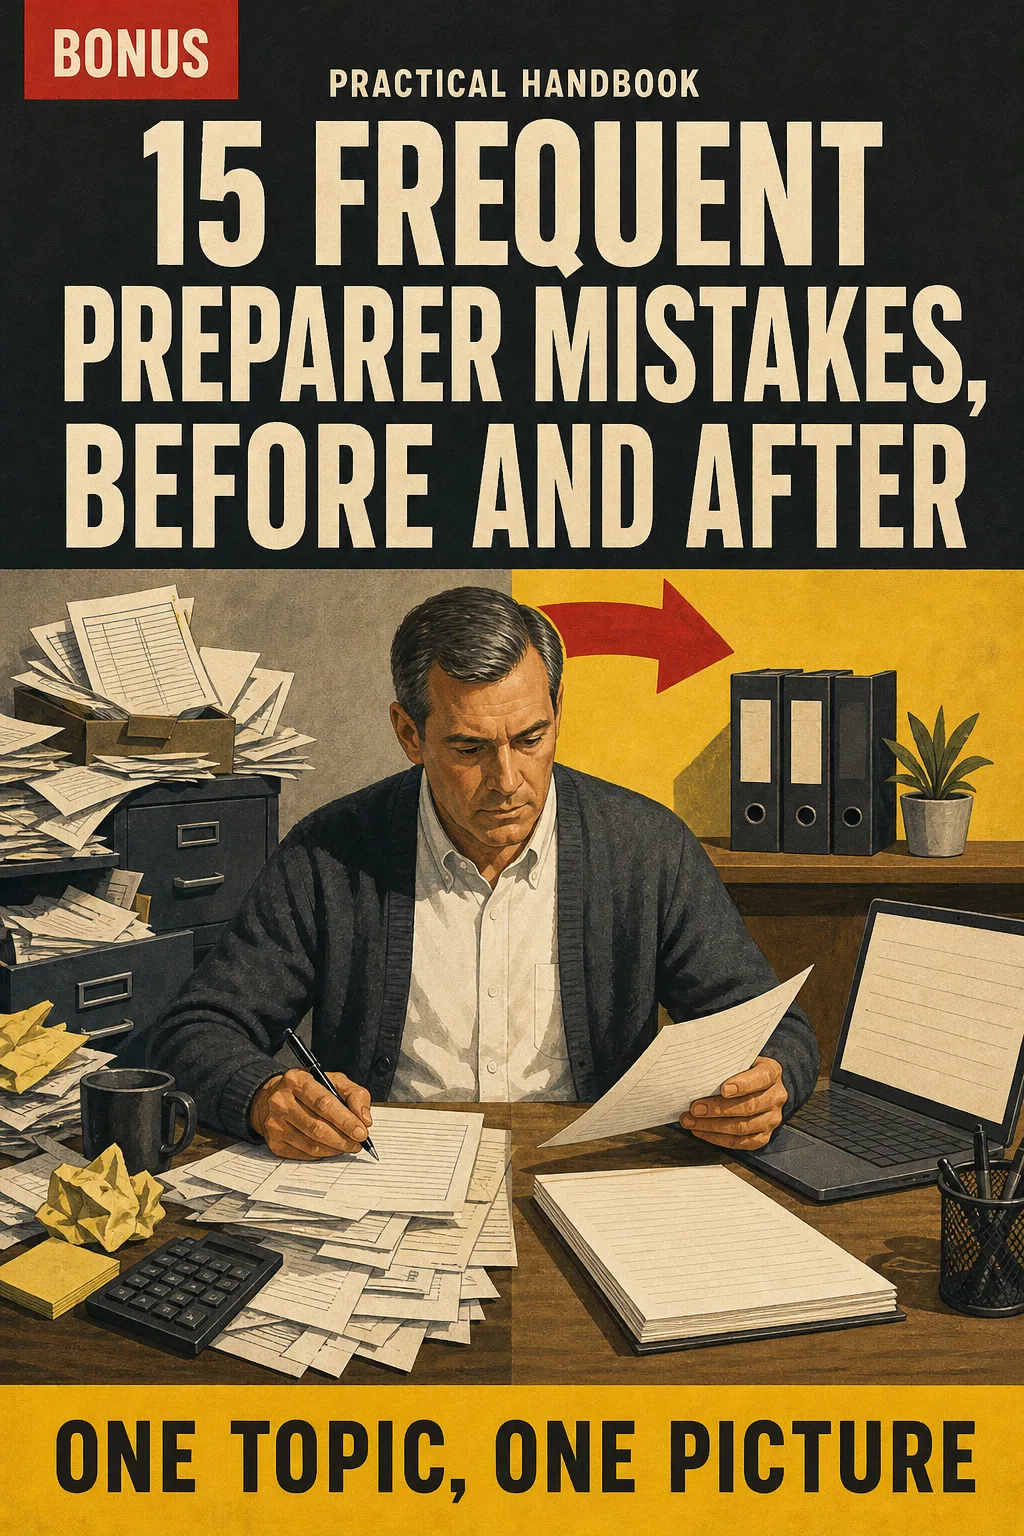
15 Frequent Preparer Mistakes, Before and After

BONUS 2: «15 Frequent Preparer Mistakes, Before and After»

Value on its own: US$ 14.90

See the slips that show up most on returns, from the wrong filing status to a missed due diligence question, drawn wrong next to right.
Tax Preparer Basics Illustrated with 2 Free Books

  • Tax Preparer Basics Illustrated: 68 illustrated pagesUS$ 63
  • BONUS 1: Refresher Test Practice: 100 Scenario Questions with AnswersUS$ 17.90
  • BONUS 2: 15 Frequent Preparer Mistakes, Before and AfterUS$ 14.90
  • High-resolution PDF to printIncluded
Total value US$ 95.80
YOUR PRICE:
US$ 27
You save US$ 68.80
YES, I WANT TAX PREPARER BASICS ILLUSTRATED FOR US$ 27

📄 This is a digital PDF book sent to your email: nothing is printed or shipped.

Secure purchaseEncrypted payment30-day guarantee

PDF by email: We email you Tax Preparer Basics Illustrated as a PDF, together with the two free books. It's a single payment: no installments, no extra charges.

Who This Book Is For

You're new to tax prep

You're new to tax prep

You see the whole return as one staircase in 9 steps, so your first clients don't feel like forty disconnected rules.

Your refresher test is coming

Your refresher test is coming

You review every topic as a drawing, then practice with 100 scenario questions before December 31.

You already prepare returns

You already prepare returns

You keep the pages on your desk and check filing status, dependents or Form 8867 in a glance while the client waits.

Everything You Get Today

US$ 95.80US$ 27
YES, I WANT TAX PREPARER BASICS ILLUSTRATED FOR US$ 27

📄 This is a digital PDF book sent to your email: nothing is printed or shipped.

30DAYS
GUARANTEE

30-Day Guarantee

Try Tax Preparer Basics Illustrated for 30 days, bonus books included.

We refund everything if the file won't open, if the book isn't what you see here, if you were charged twice or if the email doesn't arrive. Just email us.

You pay once. No subscriptions.

Frequently Asked Questions

Is it for me if I already prepare returns every season?

Yes. It's a review, built the way you work the return: from the interview to e-file, always in the same order. If you're new, it gives you that order from day one. It covers the federal Form 1040, not state returns.

Where does the content come from?

From current IRS publications and forms: Publications 17, 501, 596, 970 and 4012, the Form 1040, 8867 and 8879 instructions, the annual inflation-adjustment revenue procedure and Circular 230. It includes the recent law changes, like the new Schedule 1-A deductions, and every dollar figure on the pages is labeled with the tax year it applies to, so you can check it against the IRS source.

Is this official IRS material?

No. It's an independent study book. It is not affiliated with or endorsed by the IRS or any continuing education provider.

Does it replace the AFTR course or give CE credit?

No. It doesn't replace the Annual Federal Tax Refresher course or its test, and it grants no continuing education credit. It's study material to review alongside them.

Are the practice questions the ones on the test?

No. The 100 scenario questions are written for this book, in a multiple-choice style, with the reason behind each answer. They are not official test questions.

When and how do I get it?

The book and the 2 bonus books arrive as PDFs by email, at the address you enter at checkout.

Do I have to pay every month?

No. It's a one-time payment. No subscription.

Can I have it on paper?

Yes. The PDF is laid out to print, one topic per page, so you can keep it on your desk or in a binder.

How does the refund work?

You have 30 days. We refund everything if the file won't open, if the book isn't what you see on this page, if you were charged twice or if the email doesn't arrive: just email us.

Before You Close This Page

No more rereading Publication 17 with nothing sticking.

Filing status? You see it drawn, and that's it.

You sit down with every client knowing where each thing is.

Drawings make studying faster.

The book is right below.

One-time payment: US$ 27 · Guarantee: 30 days · PDF by email

YES, I WANT TAX PREPARER BASICS ILLUSTRATED FOR US$ 27

📄 This is a digital PDF book sent to your email: nothing is printed or shipped.